What Not to Say to an Insurance Adjuster
A single spring hailstorm or a summer windstorm can leave hundreds of Pittsburgh area roofs damaged in one afternoon. What you say and do during the insurance claim that follows can shape the outcome more than most homeowners expect.
When you speak with an adjuster, do not admit fault and do not guess at the cause. Stick to the facts you know: when the storm hit, what you saw, and where water came in. Let a roofer who has been on the roof explain the technical details. Above all, do not say "it is not that bad." A casual comment like that can be used to justify a smaller payout.
The best first step is a professional residential roof inspection before the adjuster visits, so you know exactly what is damaged and have photos to back it up. In this guide we walk through navigating roof insurance claims in Pennsylvania in 2026, step by step, with the mistakes we see homeowners make most often.
How to Make a Successful Roof Leak Insurance Claim
Filing a successful roof insurance claim starts with thorough documentation and a roofing contractor you trust.
Step 1: Assess Damage Safely
From the ground and from inside the house, look for visible signs of damage like:
- Missing, creased or lifted shingles
- Leaks or new water stains on ceilings and walls
- Shingle granules collecting at the gutter downspouts
- Debris or fallen branches on the roof
- Dented gutters, vents or flashing after hail
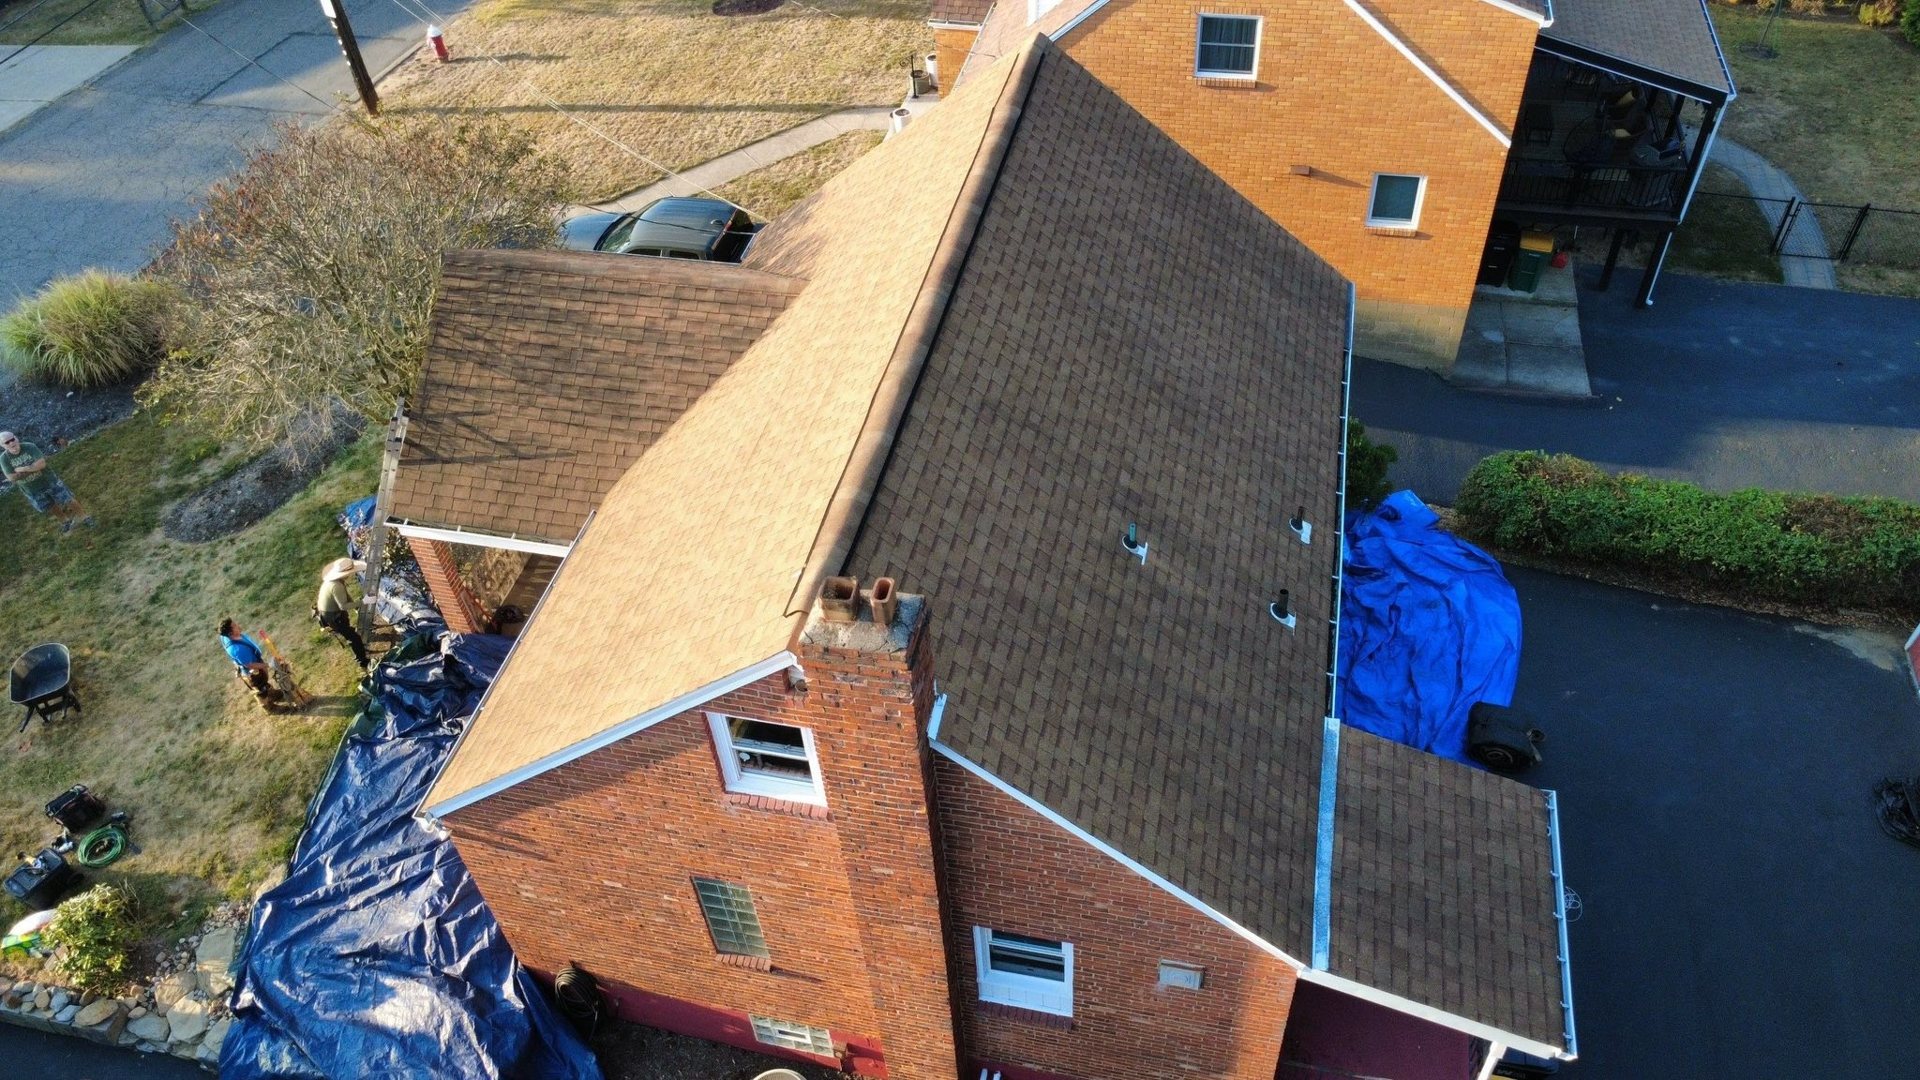
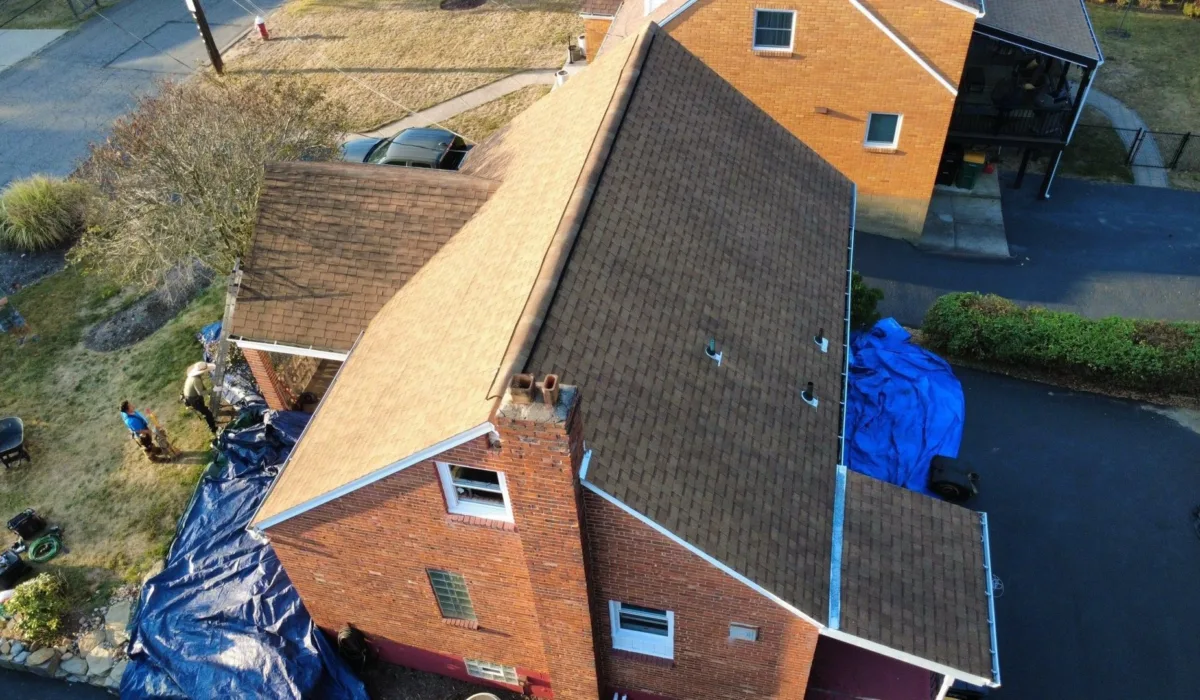
Never climb onto your roof, especially when it is wet. Instead, schedule a roofing inspection for insurance with a professional crew like ours at Malick Brothers Exteriors. We document what we find with photos and a written report you can hand to your insurance company.
If water is coming in, take reasonable steps to limit further damage, such as moving belongings and catching drips, and keep receipts. Most policies expect you to prevent additional damage once you know about it.
Step 2: Understand Your Policy
Before filing, find out:
- Whether your policy covers storm damage such as wind, hail and falling trees
- Your deductible, and whether there is a separate wind or hail deductible
- Whether your plan pays actual cash value (ACV) or replacement cost value (RCV)
- Any exclusions for roof age, wear and tear, or lack of maintenance
- How long you have to report damage and to finish repairs
Policies vary widely, so ask your agent these questions up front. With an ACV policy, the payment is reduced for the age of the roof. With an RCV policy, the insurer often pays the depreciated amount first and releases the rest after the work is complete and documented.
Step 3: File Promptly
Time matters. Call your insurance provider and have the following ready:
- Date and cause of damage
- Photos and the contractor inspection report
- Any notes or videos from the event
Delays can lead to denied claims or reduced payouts, because the longer you wait, the harder it is to prove the damage came from a specific storm and not from age.
Why Pittsburgh Roofs Take a Beating
Western Pennsylvania weather is hard on roofs. Summer thunderstorms bring strong straight line winds and occasional hail. Winters bring heavy snow, freeze and thaw cycles, and ice along the eaves. Many homes in neighborhoods across the North Hills, the South Hills and the city itself are older, with steep roofs, mature trees overhead and several layers of past repairs.
That mix matters for a claim. An adjuster has to decide whether damage was caused by a covered event or by years of weathering. A roof that already has worn shingles, failing flashing or old patches is easier for an insurer to label as wear and tear. Clear photos taken soon after the storm, plus an inspection report that separates fresh storm damage from older issues, help your claim stand on the facts.
Will Home Insurance Cover a 15 Year Old Roof?
Maybe. Many policies reduce or deny coverage for older roofs, especially if damage is attributed to age or lack of maintenance.
However, if a recent storm caused the damage, it may still be covered, especially if you can show records of past inspections and repairs.
If your roof is nearing or past 15 years old, talk with your contractor and insurance agent about the risks before the next storm season. Some insurers change how older roofs are covered at renewal, so read any policy change notices carefully.
Is It Worth Claiming Roof Damage on Insurance?
It depends on the scale of damage and your deductible. Minor damage that costs less than or only slightly more than your deductible may not be worth filing, since a claim can still appear on your insurance history.
For more significant damage, like widespread storm damage roof repair or a roof that needs to be replaced, filing usually makes sense. A free written estimate from a roofer helps you compare the repair cost with your deductible before you decide.
If you are unsure whether to proceed, a Pennsylvania attorney can explain your rights under your policy. Tighe P.A. offers helpful insights into when and how to file a claim.
Working with the Adjuster
Once your claim is in, your insurer will assign an adjuster to inspect the roof. It is wise to have your roofing contractor on site during that visit to:
- Make sure nothing is missed, including flashing, vents, gutters and siding
- Explain technical damage such as creased shingles and hail bruising
- Point out code items that a proper repair would require
When we meet an adjuster, we walk the roof together and show what we documented. We are there to make sure the damage is seen and measured accurately. The claim itself stays between you and your insurance company, and the final decision is theirs.
Finalizing the Claim
When the adjuster submits a report, you will receive an estimate, often called a scope of loss. Compare it line by line with your contractor's written estimate. If items were missed, your contractor can document them so you can ask your insurer to review the claim again with a supplement request.
After approval:
- Sign the contract with your roofer
- Schedule the work
- Save all invoices, photos and final reports
Submit final documentation to your insurer so any held back depreciation can be released. Keep copies of all communications for your records.
Avoiding Claim Denials
Even a valid claim can be denied if steps are missed. Common pitfalls include:
- Failing to report damage promptly
- Inadequate photos or documentation
- Making permanent repairs before the adjuster has seen the damage
- Using an unlicensed or uninsured contractor
Hiring a qualified roofer and keeping clear records at every stage reduces your risk. In Pennsylvania, home improvement contractors must register with the Attorney General, and you can ask any roofer for their registration number. Ours is PA174918.
Why Pittsburgh Homeowners Call Malick Brothers
Malick Brothers Exteriors is a family owned roofing company founded in 2022 by Ryan Malick, working out of our shop on Perry Highway in West View. We are BBB A+ accredited and an AtlasPro+ Platinum Select contractor. When a storm damaged roof needs to be replaced, complete Atlas roof systems we install can carry Atlas's 50 year warranty. We handle shingle, metal and low slope roofs, slate repair, siding and seamless gutters, so one crew can address everything a storm touched.
Roof Insurance Claim FAQ
Should I get a roof inspection before I call my insurance company?
Yes, if you can do it quickly. An inspection tells you whether there is real storm damage worth claiming and gives you photos and a report to support the claim.
Can I make temporary repairs before the adjuster comes?
Usually yes. Most policies expect you to prevent further damage, such as tarping an opening. Photograph everything first, keep receipts, and hold off on permanent repairs until the adjuster has inspected.
What if my claim is denied or the payment seems too low?
Ask the insurer for the reason in writing, review your policy, and request a second inspection if new evidence is available. A contractor can document missed items, and a Pennsylvania attorney can advise you on your options.
Does filing a claim raise my premium?
It can. That is one reason to compare the repair estimate with your deductible before filing. Your insurance agent can explain how a claim may affect your policy.
Your Next Steps with Malick Brothers Exteriors
If a storm has hit your roof, call Malick Brothers Exteriors at 412 616 0191 or contact us online to schedule your free inspection and written estimate.